How OEMs can turn connectivity into recurring revenue
Covers packaging video safety as subscription services, growing service attachment after the sale and what fleet customers are willing to pay for.
Share


How OEMs can turn connectivity into recurring revenue
Connectivity became standard equipment before it became a business. Berg Insight counts 338 million OEM-connected vehicles on the road, with 83 percent of new cars shipping connected and 91 percent expected by 2030, while the same analysis notes automakers giving core connected services away free for extended periods just to keep users engaged. Recurring revenue comes from services that deliver outcomes a customer can measure, and safety services lead that list because their value shows up in claims files and insurance premiums rather than in feature lists.
Connected vehicle data monetization has been promised to boards for a decade, and the gap between forecast and income has usually been the service itself. Map data, infotainment and remote lock apps face free competition from the phone in every driver's pocket. Safety intelligence about a company's own fleet has no free substitute, which is why it renews.
The attach-rate problem nobody escaped
The consumer playbook produced its own cautionary tales. Free trials lapse quietly, feature paywalls for hardware already in the car generate resentment rather than revenue, and subscription fatigue means every automaker's app competes with every streaming service for the same wallet. Renewal rates on consumer connected packages stay stubbornly low because the value is episodic, a remote start here and a stolen vehicle locator hopefully never. The lesson is not that vehicle subscriptions fail, it is that subscriptions detached from measurable outcomes fail.
Commercial customers run on different math. A fleet operator evaluates a per-vehicle monthly fee against claims avoided, premiums stabilized and drivers coached, and renews when the numbers work. Business buyers also purchase across whole fleets rather than one seat at a time, which turns each contract into hundreds or thousands of subscriptions with a single renewal decision. The revenue quality difference is the whole argument for leading with fleet-facing services.
The safety revenue stack
Safety services monetize through several layers at once, and mature programs run most of them together. The table below lays out the stack from the point of sale onward.
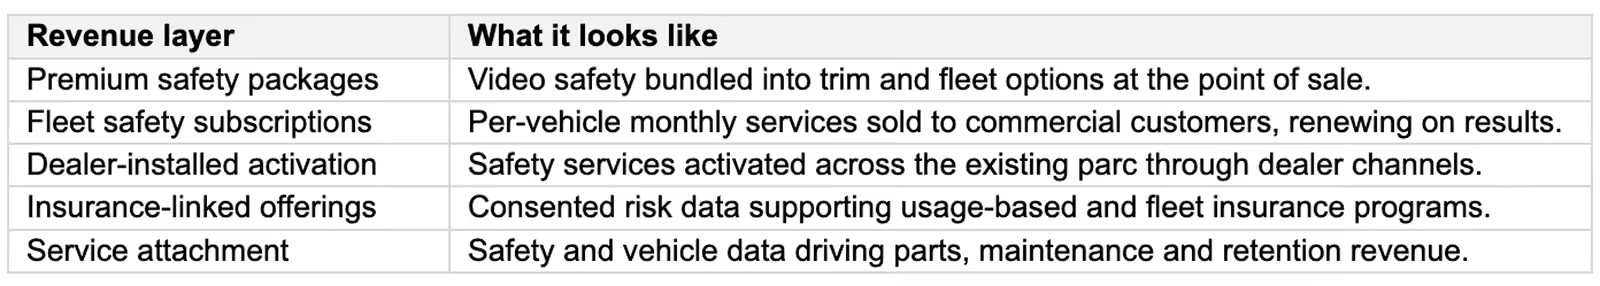
Each layer reinforces the next. A vehicle sold with embedded safety capability becomes a subscription candidate, a subscribing fleet becomes an insurance program candidate, and every layer deepens the customer relationship that service revenue depends on.
Why do fleet customers keep paying?
Renewal follows measurement. A fleet running video safety watches distracted driving and speeding fall, sees claims resolve with evidence instead of lawyers, and reads the results in quarterly reports, and cancelling a service that visibly pays for itself requires a braver CFO than most. Providers delivering video safety see revenue per user roughly double on average once the service attaches, which reflects what outcome-backed services command over connectivity alone. The subscription survives budget reviews for the same reason insurance does, because the cost of not having it is documented.
A business case finance will sign
The unit economics work when the launch cost stays small and the channel stays warm. A white label platform turns the service into subscription economics without an AI lab on the payroll, launches measured in weeks put revenue in the same fiscal year as the decision, and distribution runs through fleet sales teams and dealer networks that already hold the customer relationships. Margin shares with the platform partner and the sales channel still leave service gross margins that vehicle sales never see, and the revenue recurs, which is the property every automotive finance model now prizes. The remaining variable is attach rate, which pilot programs with existing fleet customers establish faster and more credibly than any forecast deck.
Execution risks are real and mostly organizational. Somebody has to sell the service, support the service and own its number, and programs stall where those roles are bolted onto teams measured on vehicle deliveries, so dealer incentives and fleet account plans need the subscription written into them. Privacy and data governance set the other guardrails, since consent structures, regional storage and event-based data collection decide what insurance-linked layers are possible in each market. The paywall backlash also taught a pricing lesson worth keeping, which is to charge for outcomes delivered by software and service, never for unlocking hardware the customer believes they already bought.
Partner selection quietly determines half of these variables. A platform provider that sells directly to fleets will eventually compete with your service, a provider without white label depth will dilute your brand at every login, and one without APIs will strand your service outside the systems fleets actually use. The structural questions, who owns the customer, whose name is on the experience and whose roadmap the service depends on, belong in the first conversation rather than the contract redlines. Chosen well, the partner disappears behind your brand and the revenue line compounds for the life of every connected vehicle you ship.
Connected vehicle data monetization FAQ
How much recurring revenue can connected services generate?
Program economics vary widely, and the strongest signal comes from safety services, where providers see revenue per user roughly double once video safety attaches. The durable metric is renewal rate rather than headline ARPU. Outcome-backed fleet services renew at rates consumer features never reach.
Why do consumer connected subscriptions churn?
The value is episodic and the competition is free, since phones deliver navigation, media and communication without a second subscription. Paywalled hardware features add resentment to the mix. Services with no free substitute and measurable financial outcomes, which describes fleet safety, hold their renewals.
What vehicle data can OEMs monetize without privacy risk?
Data that is consented, purpose-bound and proportionate, which in practice favors event-based architectures over continuous collection. Fleet programs simplify consent because employers, drivers and providers operate under explicit policies. Regional storage and recognized certifications keep programs inside the lines as rules evolve.
Price the outcomes, not the hardware
Count the connected vehicles you shipped last year and the recurring revenue they returned, then compare that against a safety service attached to even a tenth of them. Our video telematics for vehicle OEMs page shows how manufacturers run the stack under their own brand. Start at lightmetrics.co.
Latest in fleet safety.
Why Insurance Leaders Are Betting on Video Telematics to Transform Fleet Risk
Why Insurance Leaders Are Betting on Video Telematics to Transform Fleet Risk
Why Insurance Leaders Are Betting on Video Telematics to Transform Fleet Risk
Get in touch with us.
If you want to learn more or want to consider offering RideView to your fleet customers, Please reach out.